
Flat roof insurance
Why do insurance companies ask if you have a flat roof?
The question is short and the answer matters. Below: how to answer it accurately, who decides what counts as a storm, and the records worth keeping.
The short answer
Insurers write their own questions and weigh risk in their own way, so only your insurer can say exactly why it asks and how it uses the answer. What we can say is what the answer should rest on: the roof's covering, its age and its condition. If the house has a flat extension, a dormer top or a flat garage roof, tell the insurer, and check the policy wording if you are unsure what counts. A true answer is always safer than a guess.
5 min read · Part of Flat roofing
Answering the question accurately
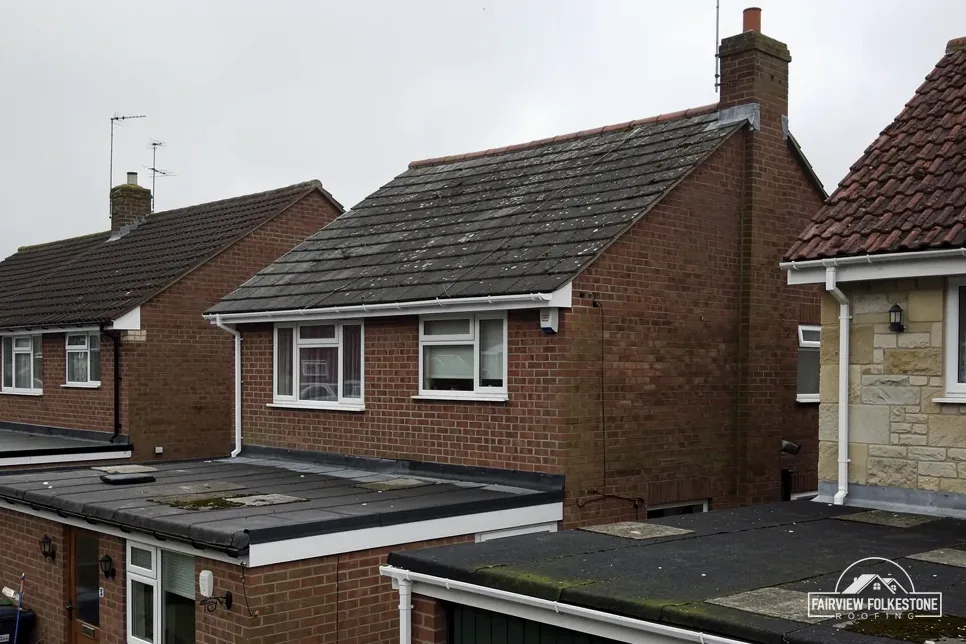
A flat roof can be the whole roof or only part of one, and the form may not ask for that detail. Give the true picture, so the policy is based on the house you own. Useful facts to have to hand:
- which parts of the house have a flat roof: an extension, a dormer top, a porch or a garage
- what the covering is: felt, EPDM rubber or GRP fibreglass
- roughly when it was last laid or renewed
- any repair or survey since, and what it found
- whether the roof has ever leaked, and what was done about it
If you are unsure of the covering or the age, a survey can say what is on the roof now. The policy documents, not our page, say what you must report and when. If the invoice for the roof has been lost, the firm that laid it, or a survey, can give a fair idea of its age.
Our flat roof lifespan answer gives the published age ranges for each covering, which is a useful check when you are working out how old a roof is, or when it might be due for attention.
Who decides what counts as a storm
Storm cover is where roof claims are argued, and the Financial Ombudsman Service publishes how it approaches them. The Financial Ombudsman Service's storm guide puts violent winds at the centre of its definition, with rain, hail or snow usually alongside, but accepts that rain, hail or snowfall alone can qualify. The Ombudsman's stated interest in photographs is why a dated picture of the damage is worth taking before anything is moved. It refers to the Beaufort Scale, and notes that some insurers draw the line at a particular wind strength on that scale.
On evidence, the Ombudsman says it will usually turn to expert reports and photographs, and that an insurer will normally commission a surveyor's report. When an insurer cites an exclusion in the policy, the burden is on the insurer to prove that it applies, for example with an inspection report.
Beyond what the Ombudsman publishes, nothing here is a rule about your own policy. The wording of your policy decides what is covered, and this page cannot see it.
Those are the Ombudsman's words about how it works, and we cannot say how any single insurer or claim will turn out. We do not handle claims.
If the flat roof leaks
Plain steps, in order:
- Tell your insurer before arranging any repair that is not an emergency.
- Stop further damage with a temporary repair, so the room stays dry.
- Photograph the roof and the ceiling underneath before anything is moved or thrown away.
- Keep the receipts for the temporary repair and anything else you pay for.
- Leave the damaged material where it is, if that is safe, until it has been looked at.
If it is dark or the roof is wet, wait for daylight before anyone goes up. A temporary repair is no reason to put a person at risk, and a room can be protected from inside with sheeting and a bucket in the meantime.
None of this depends on the make of the roof, and none of it is a promise about what the insurer will pay. A survey then says what the roof needs: a patch if the membrane is sound, or a new membrane where it has failed.
The flat roofing page explains how that verdict is reached and what the written price covers.
Records worth keeping after roof work
After a new roof or a major repair, keep a short file where you can find it again:
- the written quote and the final invoice
- photographs of the finished roof, including the edges and the outlets
- a note of the covering and the build-up that went on
- the date the work was finished
- any survey report, with the date it was written
- a note of earlier repairs, with their dates
These help with a later insurer question, a sale or a survey. They also answer the question of when the roof was last renewed without guesswork.
If a claim is declined and you disagree, begin by complaining to the insurer. The Ombudsman's guidance gives a business up to 8 weeks to consider a complaint, and you then have 6 months after its final reply to refer the matter on. Keep copies in one place, such as a folder on your phone, since paper gets lost. A record kept as the work happens is easier than one rebuilt years later. The Financial Ombudsman Service helpline is 0800 023 4567.
More questions
Should I tell my insurer after a new flat roof is laid?
Your policy documents say what you must report, so check them or ask the insurer. A new roof changes the facts the insurer holds about the house, and the quote, invoice and photos of the finished work make that conversation easy. We do not arrange or comment on cover, so put the question to your insurer.
What if my insurer turns down a claim for a flat roof?
Take your complaint to the insurer first, which has up to 8 weeks to respond for most complaints. After its final response you have 6 months to go to the Financial Ombudsman Service, on 0800 023 4567. Keep the photographs, any surveyor's report and the receipts together in one place.
Tell us what's wrong with the roof.
You'll get one written total price.