
Insurance
Does spray foam insulation affect home insurance?
The concern RICS reported sits in lending, and your own policy wording is a separate matter. Below: what to ask, in what form, and what evidence helps.
The short answer
Your policy wording decides, and only your insurer can confirm it. The concern RICS reported in March 2023 was in specific sectors of the lending market, such as equity release mortgages, and not in buildings insurance. Tell your insurer about the foam in writing, keep the reply, and put the same question to your lender before any work starts.
5 min read · Part of Spray foam removal

What has been reported about foam
Two organisations have said something useful on this subject, and neither of them was speaking about insurance. Both pieces of advice are worth knowing before you phone anyone.
- A RICS press release of March 2023 reported "concern within specific sectors of the lending market, such as equity release mortgages", with a wider impact on lenders following.
- The same body's consumer guide advises owners to ask their mortgage provider whether its policy allows such products.
- The Energy Saving Trust writes that there "should be less of an issue with getting a mortgage" where the foam was installed correctly.
Look at the hedges: concern, specific sectors, should be less. Nothing in these statements says an insurer will refuse cover, load a premium or void a policy, and a writer who claims so has gone past the evidence. What your policy says about alterations, roof condition and upkeep is for your insurer to answer, in terms you can keep on file for the future, and the next section lists what to put to them. Until that reply arrives, treat any firm statement about insurance and foam, from any website, as unproven, including this one.
What to ask your insurer
Questions are best put by email or letter, in your own name as the policyholder, so that the reply is on file if the roof is ever the subject of a claim. Number them, as below, so each one gets its own answer.
- Does the policy have any condition about insulation added to the roof space, and does foam need to be declared?
- If the foam is taken out, does the work need to be notified beforehand?
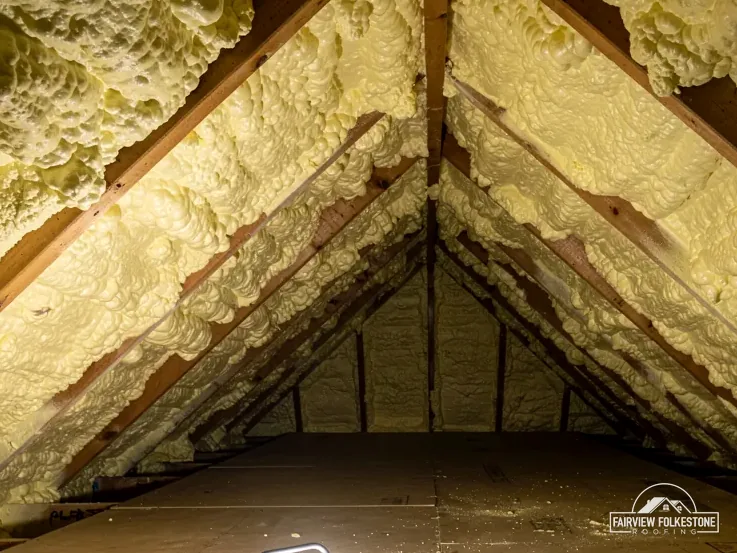
- Does the insurer want a survey report on the roof timbers, given that foam hides them?
- Will the insurer confirm in writing that cover continues while part of the roof is open to the weather during the work?
Ask whoever holds your mortgage the first question as well, because a lender's rules are a different document from your insurance schedule. A seller or a buyer will want both replies to hand, and our guide to spray foam removal before selling shows where they fit in a sale. Keep the answers with the policy so they travel with the house. If the insurer asks for a survey of the roof timbers, our survey is the step that opens a test area and takes the readings, and the report can be passed on in full.
Evidence that helps if the roof is damaged
A roof with foam under it still meets storms, and the Financial Ombudsman Service sets out how storm complaints are judged. In the Ombudsman's wording even rain, hail or snowfall by itself can constitute a storm, and photos and expert reports are what it will usually look at. When an insurer cites an exclusion, the insurer has to prove it applies, for example by producing an inspection report. A report of that kind is far easier to write when the roof timbers were seen and probed before the damage, rather than hidden under foam.
Dated evidence therefore matters, before and after any work:
- Photographs of the loft and the roof taken before anything is moved, with the date on each.
- Moisture readings and notes on timber condition from a survey.
- Receipts for any emergency covering put up.
- The written replies from your insurer to the questions above.
After damage, tell your insurer first, then have a temporary repair done so the house is weathertight, and keep every receipt. A complaint goes to the firm first, which has up to 8 weeks for most complaints, and the Ombudsman's helpline is 0800 023 4567.
Keeping the paperwork together
Whether the foam stays or goes, the records that serve you with an insurer, a lender or a buyer are the same, and they are easy to lose if nobody gathers them in one folder.
After a survey of a foamed roof, the photographs and moisture readings are yours to pass on. They show the state of the timber on a named date, which matters because RICS notes that foam over a roof structure stops it being fully seen or inspected. If the foam is taken out, the same set is repeated afterwards, giving a before and an after, with whatever goes back, such as felt, ventilation and insulation, described in the written paperwork. A buyer's surveyor reading those pages sees a roof that has been opened, checked and finished.
The written total is one price. If you sign at home after the survey you have 14 days to cancel, and a start inside that time needs your written request. Our spray foam removal page explains the whole process, and the spray foam survey answer lists what a report records.
More questions
Do I have to tell my insurer about spray foam?
Policies differ, and the wording of yours decides. The safe course is to ask in writing whether foam in the roof space needs declaring, and to keep the reply with the policy documents. A written answer is worth more than a phone call, and it settles the point if the roof is ever claimed on.
Would removing the foam help with a mortgage or sale?
It may remove a question, though that is not promised. RICS reported concern in specific sectors of the lending market, while the Energy Saving Trust expects fewer mortgage problems for foam that was installed correctly. Ask your lender, or the buyer's lender, what evidence they want to see.
Tell us what's wrong with the roof.
You'll get one written total price.